Since 2018
For over 8 years, we've helped clients navigate Polish law, combining our solid legal knowledge with practical immigration experience.
ONE PLUS helps foreign entrepreneurs prepare to open a business bank account for a JDG or limited company in Poland. We first review the business form, identity and residence documents, PESEL, registry data, ownership structure, planned transactions and the bank’s KYC requirements.
For a JDG, we check the CEIDG entry and the owner’s connection with the activity. For a company, we also review KRS, NIP, REGON, CRBR, management authority and beneficial-owner documents. We help organise translations, select a suitable account type and prepare for branch or remote identification.
The client approaches the bank with a coherent file and can clearly explain the source of funds and business model. The bank alone decides whether to open the account, but complete and consistent documents reduce avoidable questions and repeat appointments.
A business account supports the company’s daily payments and records. It is how you collect client payments, pay suppliers, handle ZUS and taxes, and show turnover to an accountant. When a business is already live but money still moves through a private account “for now”, banks, contractors and bookkeepers raise questions sooner than most founders expect.
During KYC, a bank reviews the foreign client and the business. Banks want a clear picture of beneficial owners, revenue model, activity address and ownership structure. An unclear explanation can lead to additional questions or refusal.
ONE PLUS has operated officially since 2018. Our team reviews the corporate and personal documents before the bank appointment. We do not promise that every bank will accept every applicant. We prepare the file and business information to reduce refusals caused by weak formalities.
Official guidance on starting a business should be checked on biznes.gov.pl. If the entity does not exist yet, finish JDG or Sp. z o.o. registration first, then go to the bank.
In practice a separate account is almost always needed. Contracts, marketplaces, bookkeeping and income evidence for residence-by-business cases are cleaner when private and business money are separated.
For a company the account is usually essential for day-to-day operations. The bank also reviews KRS, NIP, REGON, management and ultimate beneficial owners.
This is where delays concentrate: no PESEL, no local phone number, a paper-only address, a generic activity description, or documents without sworn translation.
A bank assesses client risk, not only a passport.
Requests commonly include:
PESEL improves odds in most branches, but it does not replace the rest of the pack. Opening without PESEL is sometimes possible, yet usually harder and more often requires an in-person visit.
Complete online opening of a business account for new foreign clients is uncommon in 2026. Most banks want branch identification or an enhanced process.
“Consulting and IT worldwide” with no website, contracts or credible address looks like elevated risk to compliance teams.
Arriving with a passport and a promise to “bring the rest later” usually creates a pause, not a fast account.
One address in CEIDG, another in the lease, a third on the form. Banks read that as a reason for deeper checks.
There is no single best bank for everyone. There is a bank that fits the scenario.
Check:
We do not push one brand as the only answer. We match options to freelance JDG, IT B2B, trade or multi-shareholder Sp. z o.o. Sometimes the right move is to strengthen the pack and address first, then book the appointment.
Often needed: passport, CEIDG, NIP/REGON, PESEL if available, Polish phone number, activity address, sometimes contracts or income proof.
Often needed: passports of management and beneficial owners, KRS, articles/agreement, NIP/REGON, CRBR, addresses, resolutions on account authority.
An account without accounting support quickly loses control of payment categories, VAT and ZUS. Bookkeeping should start in the first month of real invoices.
We start with diagnosis: JDG or company, who signs, whether PESEL exists, planned turnover, and whether the account is urgent for a contract.
Then we usually:
If the business is not registered yet, we first handle JDG or Sp. z o.o.. If the identifier is missing, we cover PESEL. For residence-by-business planning we add a business plan.
Office: Wrocław, Piłsudskiego 43. The bank decides whether to open the account. Our role is to reduce refusals caused by a raw file.
If you need a business bank account and want a cleaner KYC path, contact ONE PLUS. We will map the next step.
Get ConsultationSometimes yes, but odds are lower. Many banks treat PESEL as baseline identification. Without it, an in-person visit and deeper checks are more common. Do not rely only on someone else’s chat experience, because branch practice differs. The decision always belongs to the bank. We prepare the pack to reduce formal refusal risk, but we do not promise a guaranteed opening.
In most new-client cases, no. Fresh JDG and Sp. z o.o. setups with foreign beneficial owners usually need branch identification or an enhanced process. Fast online onboarding more often applies to private accounts or already verified clients. Collect a complete pack and book a branch that actually serves foreign business clients.
Typically: passports of management and beneficial owners, current KRS extract, company documents, NIP/REGON, CRBR, addresses and sometimes resolutions on signing rights. Foreign-language papers almost always need sworn translation. The clearer the ownership structure, the fewer extra KYC questions appear.
For JDG the bank looks at a natural person running activity. For Sp. z o.o. it assesses corporate structure and beneficial owners. Product packages and fees also differ. Do not mix these scenarios in one file. If the business form is still open, decide first between JDG and Sp. z o.o..
Very often yes. Phones are used for authorisation, addresses for correspondence and reality checks on the business. A virtual address is sometimes accepted, but a weak activity story raises review risk. Align contacts and address before the visit so they match the registries.
Identify the reason first: documents, beneficial owners, activity type, risk country or incomplete KYC. Walking into the next bank with the same incomplete file often produces the same answer. Sometimes you need registry updates, translations or PESEL first. ONE PLUS has helped analyse refusals and prepare stronger second approaches since 2018 when that path makes sense.
Ideally in the first month of real payments. An account without bookkeeping support quickly loses control of cost categories, VAT and ZUS. The account and the books should work as one system.
Opening the account does not replace the legal ground for residence. Transparent turnover and a readable banking history often help show that the activity is real. The residence decision belongs to the office, not the bank. If residence-by-business is on the roadmap, align the account, business plan and accounting documents early.
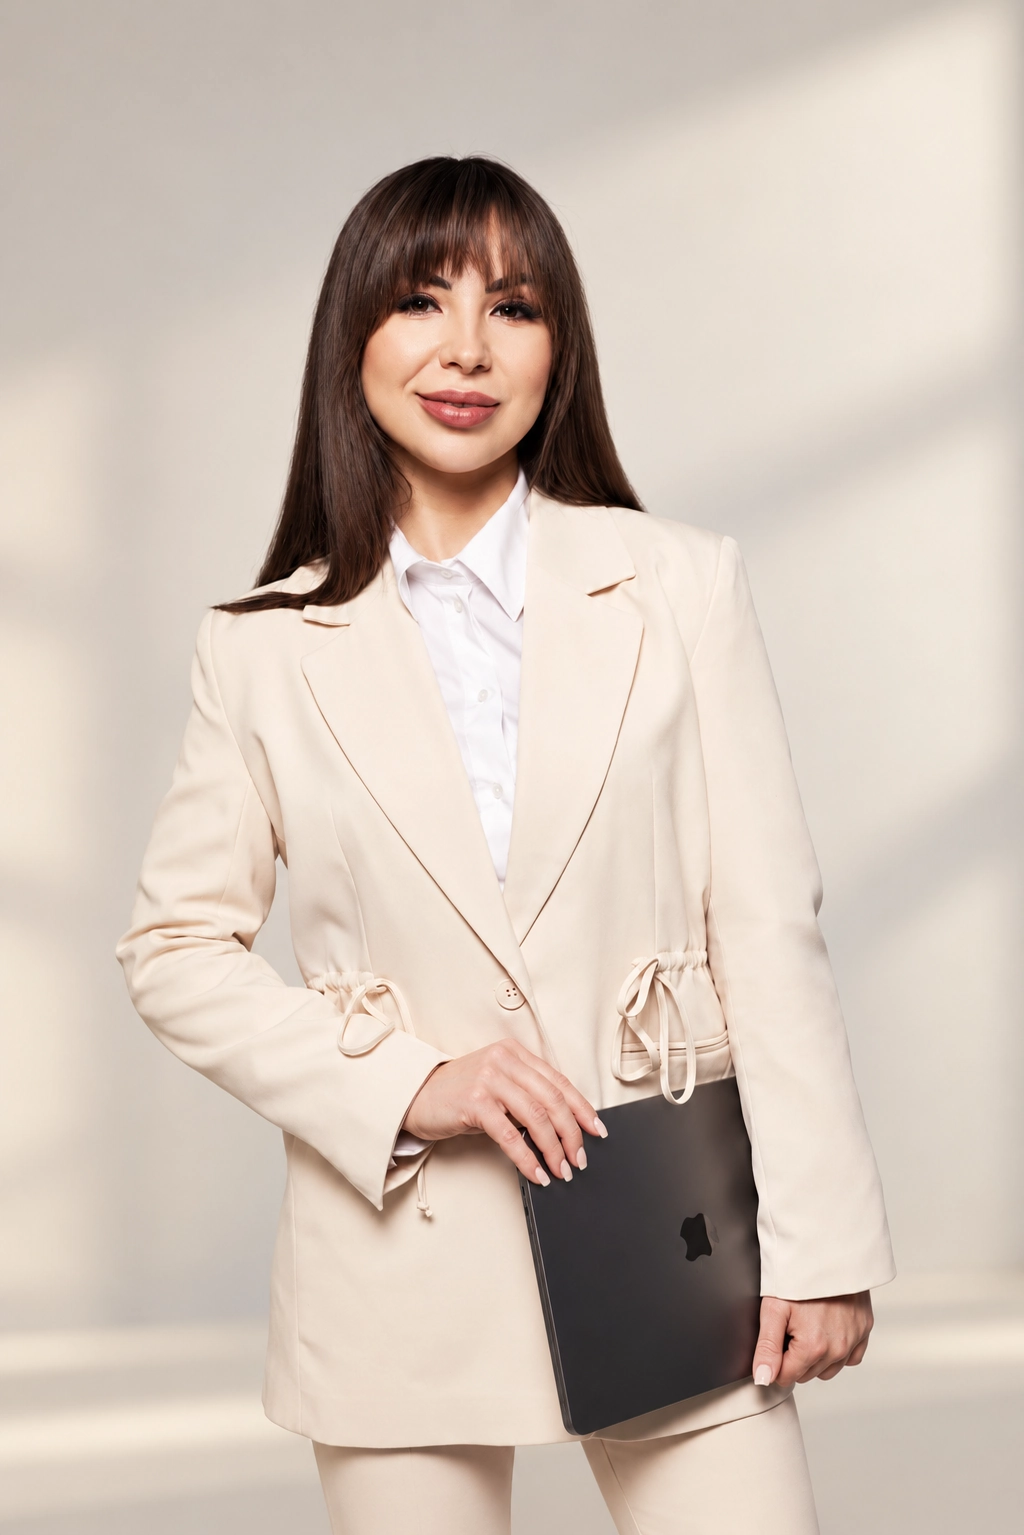
Certified Specialist in the Legalization of Stay and Employment of Foreigners in Poland. Tatiana is a graduate of Uniwersytet Ekonomiczny we Wrocławiu and Uniwersytet Wrocławski, where she completed studies in Legal and Business Consulting, followed by the postgraduate program Legalizacja zatrudnienia cudzoziemców at Uniwersytet Wrocławski.
With more than 12 years of professional experience and daily cooperation with Polish government institutions, Tatiana has developed an effective approach to resolving even the most complex immigration matters. She provides clear legal guidance, assists with document preparation, and supports clients throughout every stage of the legalization process.
Her individual approach, in-depth knowledge of Polish immigration law, and practical experience make the legalization process straightforward, secure, and as smooth as possible for every client.
I decided to contact this company on a friend's recommendation. To be honest, I don't regret it! They helped me with the formalities of registering my company, which operates in a foreign country and can be difficult to handle on your own. They handled everything within the agreed deadline and without unnecessary problems. They always respond and help solve even the most difficult problems. Thank you very much for your cooperation.
A very nice and mega professional company. Thank you very much Tatiana for the professional cooperation and support at all stages of getting permanent residence. They handled their business very quickly and professionally, I was satisfied and I plan further cooperation in order to get more documents…
Thank you One Plus!!! For your work, professionalism and high quality approach to business. I received the decision quickly and now I am waiting for the plastic surgery. Thank you very much and I highly recommend to everyone!!!
I registered the reel through ONE PLUS. I really liked how fast it was, the whole procedure took only 2 days. Great!
I really like the ONE PLUS agency. The service is excellent. They always pass on information politely and competently. They handle all the necessary documents as expected, step by step. The coordinators take their tasks seriously and help in every situation. Thank you very much to everyone. I recommend them to my friends and family :)
Excellent company! They provided a comprehensive consultation on tax settlement, helped me handle all the necessary procedures and answered all my questions in detail. And all of that in a short time. I have no doubts about their professionalism and the quality of their services! :) I recommend them 100%!
I had a paid consultation about setting up a company in Poland and received comprehensive answers to my questions. We look forward to further cooperation. Thank you.
We applied to One Plus for registration as a sole proprietorship. Later we applied for permanent residence. Collecting the documents did not take long. We submitted the application at the beginning of December, and the document was issued at the beginning of June. Everything went quickly and smoothly. Now we are waiting for our plastic card.
Good day everyone!!!! I want this company to only broaden its horizons!!! You do very high quality and solid work!!! You help with documents! Those girls on the team! Very friendly... They inform about all events!!! They consult online!! SUCCESS in business! Grow your ENTERPRISE!!!! You helped me a lot! And I hope!!! That thanks to the huge work you have done!!!!! Another 10,000 people will change their lives for the better! And people will be able to move forward!! Even faster. P.s. I HIGHLY RECOMMEND YOU TO EVERYONE FROM THE HEART!!!!!!! YOU ARE PEOPLE WHO KEEP THEIR WORD! THANK YOU ONCE AGAIN, IT IS A PLEASURE TO WORK WITH YOU!
I was looking for advice on setting up a company in Poland. They explained everything to me clearly and simply, and also helped me sort out the formalities and nuances. Thank you ☺️
Thank you very much, I opened my own business with the help of ONE PLUS. Fast, efficient and inexpensive. They are true professionals. I highly recommend them.
The best company that will bring a case to a positive outcome, help you obtain compensation from unfair inspectors and provide competent advice to Wroclaw entrepreneurs. I submitted an application in 2019, the inspector changed 3 times, I received compensation of 2400 zloty and a decision on business activity. And all thanks to One Plus and Tatiana, who handled my case from the very beginning. Without any additional fees, the compensation turned out to be higher than the cost of the service. Thank you for the "walk" with the office and for the professionalism of the whole team!
Nice office, they sorted out my residence card insurance very quickly. I highly recommend them!
I needed a consultation about a residence permit and later relocation from Poland. The specialist explained the nuances of my situation to me and pointed out issues I had not thought about before. After the consultation it became much clearer to me what to do next.
I am very grateful to ONE PLUS for their help in the process of legalizing my stay. Special thanks go to Tatiana, I could always count on clear explanations, quick answers and support at every stage.
I contacted ONE PLUS about a Polish residence permit. I needed to sort out my documents and understand how to go through all the stages of the application correctly. I received legal advice, help with preparing the necessary documents and explanations about the next steps. Everything became much clearer; I didn't have to search through various sources myself. Thank you for the help and support.
I would like to thank ONE PLUS for their help in handling the formalities. It was my first time with this company and I was pleasantly surprised. They were always available, guided me fully through all the matters and answered questions, helped me and explained any doubts. Everything went quickly and smoothly, thanks to highly qualified specialists.
I am very satisfied with the help. I needed advice about legalization and registering a residence card in Poland. They helped me organize the documents, checked everything and explained what to do and how. Thanks to them the whole process went much more smoothly. I recommend!
Great office, they answer and respond very quickly. They helped me and my parents, even though we had a difficult situation. Not even half a year passed and my dad got the card from the injured party. I recommend them to everyone, you won't regret it :)
I submitted a residence permit application. Everything was explained to me in detail, without unnecessary bureaucratic language. I especially liked the consultation about legalization, after which it became much clearer what to submit and where.
Call Mon-Fri 09:00-17:00
 +48 71 880 85 08
Contact us online


We’ll call you back during business hours.
 We will tell you more about servicesInitial client consultationExpress situation audit
During business hours
Your data stays secure
Support with your case

 4,7